Investing in the AI Supply Chain: Who Gets the Dollar, and Who Keeps It
Every AI headline eventually becomes a purchase order. When Microsoft or Meta raises its spending plan, that money doesn't vanish into "AI." It lands on specific income statements: Nvidia's for accelerators, TSMC's for wafers, SK Hynix's and Micron's for memory, ASML's for the machines that print chips, Vertiv's for cooling, and so on down a chain that ends at a German optics maker and a few Japanese chemical companies.
For investors, the useful question isn't whether AI is real. It's who gets each dollar of AI spending, and who gets to keep it. This piece maps the supply chain from top to bottom, then uses four years of price history to show how the money has actually moved through it since ChatGPT launched, and how each layer behaves when the mood turns.
The short version
- The money starts at the top. Microsoft, Alphabet, Amazon and Meta plan to spend $720 to $745 billion on capital projects in 2026, up about 80 percent in a year, and a growing share is funded with debt, new stock and partners' money.
- It has rewarded whatever was scarce. Since ChatGPT launched, market leadership has moved down the stack: chip designers in 2023, power and networking in 2024, memory, optics and chip equipment in 2025 and 2026. Micron is up about 19-fold. The hyperscalers writing the checks are up about 2.6-fold.
- Pricing power lives where the alternatives don't. The design-software toll collectors and Nvidia keep the most of each dollar. Right now so does memory, which says a lot about how far the memory cycle has run.
- Depth is not the same as risk. Classic chip downturns hit all of silicon about equally. AI-specific scares hit the purest AI plays hardest, wherever they sit.
- The weak links are financial. Oracle's downgrade, the neoclouds' debt and suppliers investing in their own customers are where the chain is most fragile.
Follow the dollar
Microsoft, Alphabet, Amazon and Meta spent about $245 billion on capital projects in 2024 and about $410 billion in 2025. Their guidance for 2026 adds up to roughly $720 to $745 billion, and they had spent about $300 billion of it by the end of June. Nobody is talking about slowing down. Alphabet expects its spending to "increase significantly" again in 2027, and Amazon says most of its 2027 capacity is already spoken for. Oracle spent $28.5 billion in the June-to-August quarter alone, more than three times its spending a year earlier.
Where does a dollar of that go? Nvidia's CEO puts the cost of a gigawatt of AI data center capacity at about $60 billion today, double what it was five years ago. Epoch AI's breakdown of a 1-gigawatt Nvidia cluster puts about 56 percent of the upfront cost into servers, 13 percent into networking and 30 percent into the building, power and cooling, and McKinsey's long-run estimate is similar. Inside the accelerators themselves, Epoch estimates that HBM grew from 52 percent to 63 percent of component costs between early 2024 and late 2025.
Behind those budgets sit contracts, many of them with AI labs. Oracle's contracted backlog stood at $664 billion at the end of August, Google Cloud's at $514 billion and Amazon Web Services' at $496 billion. OpenAI and Anthropic, both still private, are the largest single sources of that demand.
Two details in these numbers matter more than the totals.
Part of the increase is inflation inside the chain. Microsoft said about $25 billion of its calendar-2026 budget reflects higher component prices, and Amazon's CEO said the cost of memory was pushing its number up. When the biggest buyers in the world raise their budgets because a supplier raised prices, you are looking at pricing power. In 2026 it has belonged to the memory makers.
The spending now runs ahead of the spenders' cash. Alphabet reported negative free cash flow in the second quarter and announced $80 billion of new equity for AI infrastructure, including a $10 billion private placement with Berkshire Hathaway. Amazon's free cash flow over the past twelve months was negative $7.6 billion. Meta's fell to $784 million in the second quarter from $8.6 billion a year earlier, and its newest 1-gigawatt campus is being built through a venture in which BlackRock puts up 80 percent of the money. Oracle carries about $125 billion of borrowings. For three years the buildout was paid for by the most profitable businesses on earth. It is now increasingly paid for with outside capital, which is more fickle than operating cash flow.
Everything below this layer depends on these companies' ability and willingness to keep writing checks.
The map
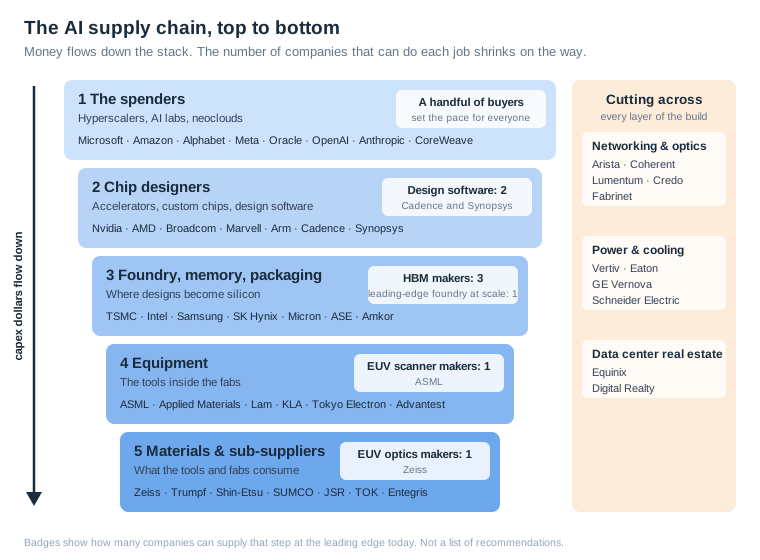
The chain has five layers, plus three industries that cut across them. At each one, the question that matters most is how many companies can actually do the job.
1. The spenders
The hyperscalers, Oracle, the AI labs and the GPU clouds create the demand. The labs are the fastest-growing buyers. OpenAI's annualized revenue is reportedly near $70 billion and Anthropic's passed $65 billion in July, and both rent most of their computing power from hyperscalers and from neoclouds such as CoreWeave and Nebius. xAI is now part of SpaceX, which listed in June. Buyers this large always try to keep more of the dollar for themselves, which is why each hyperscaler also designs its own chips: Google's TPU, Amazon's Trainium, Microsoft's Maia and Meta's MTIA.
Above them sit application companies such as Palantir, ServiceNow, Salesforce and Adobe. They are customers of the stack rather than part of it, but we track them in the charts below as a gauge of whether AI spending is turning into AI revenue.
2. Chip designers and the toll collectors
Nvidia is still the center of gravity. It reported $96.2 billion of revenue in the quarter ended July 26, up 106 percent, at a 75 percent gross margin, and described next year's growth as limited by supply, not demand. AMD is the main merchant alternative, with data center revenue up 107 percent and gigawatt-scale deals with both OpenAI and Anthropic.
The fastest-growing corner is custom silicon. Broadcom's AI revenue reached $16.7 billion last quarter, up 221 percent, from six custom-chip customers including Google, Anthropic, OpenAI and Meta. Marvell is the other major design partner. TrendForce expects custom chips to power about 28 percent of the AI servers shipped this year. The startups have had a rougher ride: Cerebras went public in May at $185 a share and now trades below that price, and Groq licensed its technology to Nvidia in a deal reported at about $20 billion.
Beneath every design sit the toll collectors. Arm's instruction set runs the hyperscalers' in-house CPUs, and Cadence and Synopsys make the design software no advanced chip can be built without. They get paid on every design, whoever wins.
3. Foundry, memory and packaging
This is where designs become physical chips, and where the chain narrows sharply.
Foundry. TSMC took 72.5 percent of global foundry revenue in the second quarter, according to TrendForce, and manufactures nearly every leading AI accelerator, Nvidia's, AMD's and the custom chips alike. It raised its 2026 growth forecast to slightly above 40 percent, and August sales were up 53 percent from a year earlier. Intel and Samsung are the only other companies attempting leading-edge logic. Intel's 18A process is in volume production and both the U.S. government and Nvidia became shareholders in 2025, but its foundry unit still lost $2.1 billion last quarter.
Memory. Every AI accelerator sits beside stacks of high-bandwidth memory (HBM), and only three companies make it: SK Hynix, with about half the market, Samsung and Micron. HBM eats wafer capacity that would otherwise make ordinary DRAM, so the AI boom has squeezed the whole memory market. TrendForce estimates that DRAM contract prices roughly doubled in the first quarter of 2026 alone. Micron reported an 86.8 percent gross margin for the quarter ended in August, higher than Nvidia's, and SK Hynix posted a 76 percent operating margin. Nvidia's own purchase commitments have climbed to $279 billion, mostly for memory.
Packaging. An AI accelerator is no longer one chip. It is one or two GPU dies joined to HBM stacks on a silicon base, a process TSMC calls CoWoS. Industry estimates put TSMC's CoWoS capacity at about 70,000 wafers a month at the end of 2025, rising to 130,000 to 140,000 by the end of 2026, and still short of demand. TSMC has begun handing some of the steps to ASE and Amkor.
4. Equipment
Foundries and memory makers buy their tools from a short list of equipment makers, and the boom has finally reached them. SEMI, the industry association, expects spending on wafer fab equipment to rise 23 percent this year to about $144 billion, and another 22 percent in 2027.
ASML is the only company in the world that makes extreme ultraviolet (EUV) lithography scanners, the machines that print the smallest features on every leading-edge chip. It has raised its 2026 sales forecast twice, to €43 to €45 billion, and plans 30 percent more EUV capacity in 2027. Applied Materials, Lam Research and Tokyo Electron split most of deposition and etch, KLA leads inspection, and Advantest and Teradyne test the finished chips.
China is the wrinkle. It bought more than a third of all chip equipment sold in 2025, by SEMI's count, and still accounts for 26 to 30 percent of revenue at Lam, Applied, KLA and Tokyo Electron. That is a risk if export controls tighten. It also means AI demand has had to fill a hole China used to fill, and so far it has: Applied's revenue grew 25 percent last quarter even as its China share fell from 35 to 28 percent.
5. Materials and the suppliers' suppliers
Some of the most irreplaceable companies in the chain are here, and several can't be bought. Zeiss makes the mirrors inside every EUV scanner and is ASML's only source for them. ASML owns 24.9 percent of that unit, and the rest belongs to the foundation-owned Zeiss group. Trumpf, a family company, makes the laser that drives the EUV light source. JSR, a leading photoresist maker, was taken private by the Japan Investment Corporation in 2024.
The investable names are mostly Japanese: Shin-Etsu Chemical and SUMCO, the largest makers of silicon wafers, and Tokyo Ohka Kogyo, which holds about 29 percent of the EUV photoresist market by one industry estimate. In the U.S., Entegris supplies filters, slurries and specialty chemicals, Qnity Electronics, spun out of DuPont in November 2025, makes polishing materials and process chemistry, and Linde supplies ultra-pure gases.
Cutting across: networking, power and real estate
Networking and optics. An AI cluster ties together tens of thousands of accelerators, and every connection is a business. Inside the rack the links are mostly copper, increasingly through active cables from Credo and connectivity chips from Astera Labs, both of which roughly doubled their revenue last quarter. Between racks they are optical: Lumentum's revenue rose 109 percent and Coherent's data center business 59 percent, and contract manufacturer Fabrinet assembles optical modules for much of the industry. Arista Networks sells the switches, competing with Nvidia's own networking business. The next shift is co-packaged optics, which moves the optical engine onto the switch chip itself.
Power and cooling. This is the constraint money can't fix quickly. Lawrence Berkeley National Laboratory estimated that data centers used 4.4 percent of U.S. electricity in 2023 and could use 6.7 to 12 percent by 2028; the Electric Power Research Institute now projects 9 to 17 percent by 2030. Gas turbines are sold out for years. GE Vernova's gas backlog and reserved production slots reached 116 gigawatts in July, and large power transformers take more than two years to deliver. Vertiv expects 30 to 32 percent organic growth this year, and Eaton paid $9.55 billion for the liquid-cooling maker Boyd Thermal. When Oracle sent a force majeure notice on a New Mexico campus in September, the reason it gave was possible power delays. For a growing number of projects, the binding constraint is the grid, not the chips.
Data center real estate. Equinix and Digital Realty own and lease the buildings. They are the most bond-like part of the chain and have traded that way, up 52 percent since ChatGPT launched, less than the S&P 500.
Who keeps the dollar
Revenue tells you who gets the dollar. Gross margin, what is left after the direct cost of making the product, tells you who keeps it, and it is the best single measure of pricing power.
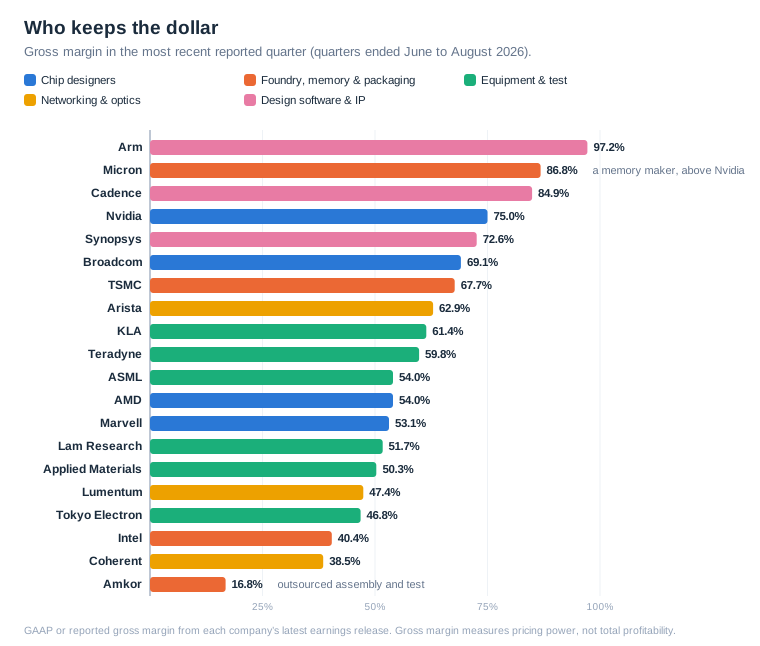
The top of the chart is what you would expect. Arm, Cadence and Synopsys sell intellectual property and software, which cost almost nothing to reproduce. Nvidia's 75 percent is extraordinary for a company that sells physical hardware, and TSMC's 67.7 percent is just as unusual for a manufacturer. Both reflect how little competition they face at the leading edge.
The surprise is Micron in second place. Memory is the textbook commodity: three suppliers making largely interchangeable products, with prices that swing every cycle. Micron's gross margin was negative as recently as 2023. A margin of 86.8 percent says the memory makers hold more pricing power right now than almost anyone in the chain. It also says how far the cycle has run.
The equipment makers cluster between 47 and 61 percent. The optics makers earn less despite their spectacular growth, because their products are closer to manufactured components than to proprietary systems. And Amkor's 16.8 percent at the bottom shows what happens to essential work in a field with plenty of competitors. Outsourced assembly and test is necessary, but it is not scarce.
The money has followed the bottleneck
A map tells you where the companies sit. It doesn't tell you where the returns went. For that we grouped the stocks named in this piece by layer and measured the median price return in each layer for every year since ChatGPT launched on November 30, 2022.
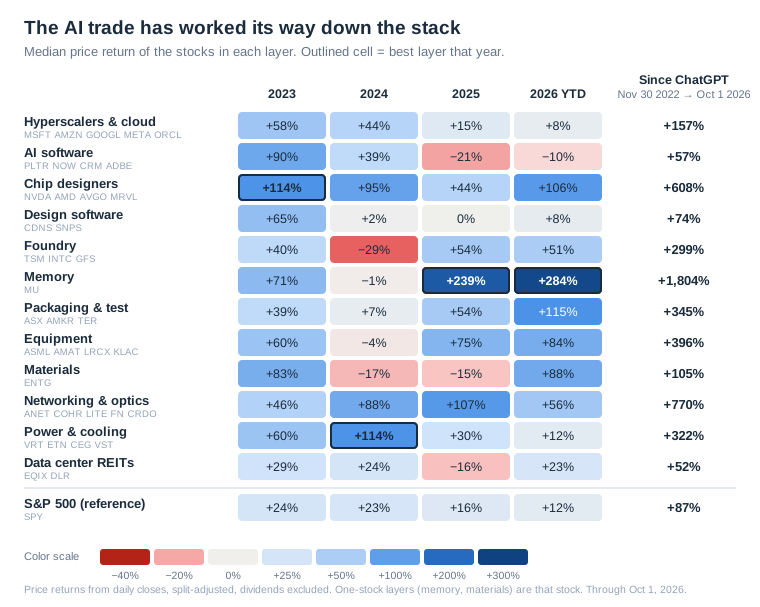
Leadership has moved down the stack, one bottleneck at a time.
2023: the chips themselves. When ChatGPT set off the scramble, the scarce thing was the accelerator. Nvidia rose 239 percent, and the chip designers led every layer.
2024: everything a GPU needs around it. Buying GPUs turned out to be the easy part. Plugging them in was harder. Power and cooling was the best layer of the year, led by Vistra (up 258 percent) and Vertiv (up 137 percent), and Credo, whose cables connect servers inside AI racks, rose 245 percent. The layers that make chips went nowhere: equipment fell 4 percent, memory was flat and Intel lost 60 percent.
2025 and 2026: memory, optics and the factory floor. As accelerators got faster, the limit shifted to how quickly data could reach them, from memory beside the chip and over fiber between racks. Micron rose 239 percent in 2025 and another 284 percent so far in 2026, and Lumentum gained 339 percent in 2025. With foundries and memory makers racing to add capacity, the equipment makers finally caught the wave: Lam Research rose 137 percent in 2025, and the equipment layer is up another 84 percent this year.
Meanwhile, look at the top two rows. The spenders have roughly matched or trailed the market for two years, and AI software has fallen in both, as investors started to worry that AI agents threaten the seat-based software model as much as they enhance it.
Three lessons come out of this chart.
The wave travels down the stack with a lag. A spending decision at the top shows up in GPU orders within a quarter, in power and networking within a year, and in memory fabs and lithography tools last, because those industries only expand once customers commit to multi-year capacity. Investors who bought "AI" in 2023 mostly bought the top of the stack. Most of the gains since have come further down.
Returns follow scarcity, not importance. Nvidia was no less important in 2025 than in 2023. It just stopped being the only constraint. The layers that soared were the ones that ran out of capacity, because a shortage is what lets a supplier raise prices.
The spenders are not the winners, at least not yet. The companies writing the checks have returned less than the companies cashing them. That will stay true until the spending turns into profit at the top of the stack, which is the open question behind the whole trade.
These are medians of small groups, so one stock can swing a cell, and memory and materials are a single U.S.-listed stock each. The point is the pattern, not any one number.
Two kinds of risk
The earlier version of this piece repeated a common claim: the deeper you go in the stack, the more cyclical the business. The data says that is only half right. Here is how each layer did in three episodes when AI stocks fell hard.
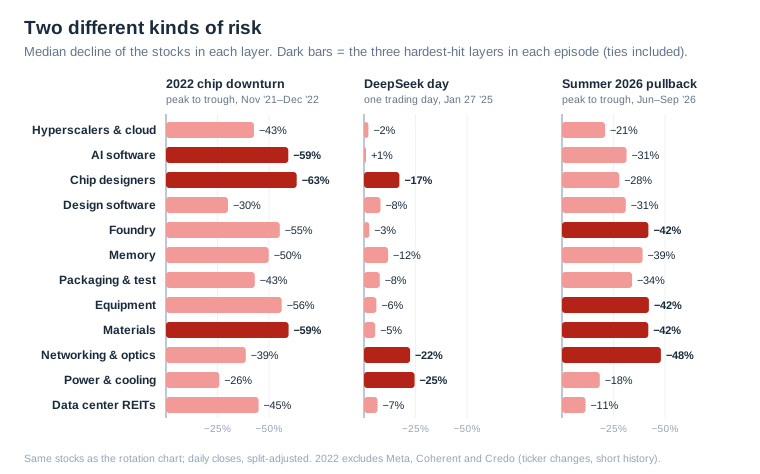
The classic chip cycle hits all of silicon. In 2022, when interest rates jumped and chip inventories piled up, nearly everything that touches silicon fell between 43 and 63 percent at the median, whether it designed chips, made them or made the tools that make them. Depth made little difference. The exceptions were the design-software makers, down 30 percent, whose subscription revenue barely moves with wafer volumes, and power and cooling, which was not yet an AI trade at all.
An AI scare hits the purest AI plays. On January 27, 2025, when the Chinese lab DeepSeek's efficient model raised doubts about how much computing power AI would really need, the worst-hit layers were power and cooling (down 25 percent in one session), networking and optics (22 percent) and chip designers (17 percent). Foundries fell 3 percent and equipment makers 6 percent. Their revenue was still spread across phones, cars and PCs, and the diversification that held them back in 2024 protected them that day.
What runs furthest falls furthest. Between late June and late July 2026, the semiconductor ETF SMH fell 25 percent while the S&P 500 barely moved. Three worries piled up at once: financing (S&P cut Oracle's credit rating to one notch above junk on July 9, and reports that Nvidia was negotiating a guarantee of as much as $250 billion for an OpenAI data center site revived talk of circular deals), a new efficiency scare when the Chinese lab Moonshot released its open-weights Kimi K3 model in mid-July, and Chinese competition in memory and chip tools. This time the hardest-hit layers were networking and optics (down 48 percent at the median), equipment, foundry and materials (42 percent each) and memory (39 percent). By 2026, those had become the purest AI plays in the market, and the ones that had run the most. The bottom came on July 29. Over the next few days Microsoft jumped 15.5 percent on strong cloud growth, Meta and Amazon joined Alphabet in raising their spending plans, and the hardware rally resumed. Still, anyone who bought the leaders at the June peak sat through a 40 percent drawdown in five weeks, in an otherwise calm market.
So the useful question isn't how deep a company sits. It is how much of its revenue depends on AI spending continuing to grow, and how much of that growth is already in the price. The design-software makers show the trade-off from the other side. They fell least in 2022, yet since ChatGPT launched they have gained 74 percent, less than half the Nasdaq 100's 153 percent. The best moat in the chain was already priced like one.
What could break the chain
Every layer below the spenders is ultimately a bet that the spending continues. These are the pressure points worth watching.
The financing at the top. S&P, which cut Oracle to BBB-, the lowest investment-grade rating, expects Oracle to spend $90 to $95 billion on capital projects this fiscal year and to run a free cash flow deficit of about $42 billion. After Oracle's force majeure notice in September, the $18 billion construction loan on the affected campus slipped below 90 cents on the dollar. CoreWeave carries about $35 billion of debt at an average rate near 8 percent, and its interest bill runs at about a quarter of its revenue. None of this means the buildout stops. It means part of it now depends on credit markets staying open.
Suppliers financing their customers. Nvidia's latest quarterly filing shows $99 billion of equity investments, another $25 billion committed, and new guarantees of up to $105 billion backing data center leases for an OpenAI affiliate. AMD gave OpenAI warrants on up to 160 million of its shares as part of a supply deal. These arrangements can be perfectly rational, but they blur the line between demand and financing. When a supplier's customers are also its investments, a slowdown can travel in both directions.
Customer concentration. A single customer accounted for 16 percent of Nvidia's revenue last quarter, and three made up 44 percent of the first half. At CoreWeave the largest customer was 36 percent. Behind many of those customers sit the AI labs. Anthropic's draft IPO filing, as reported by Reuters, shows about $518 billion of compute commitments, roughly eight times its current annual revenue run rate, and an OpenAI investor presentation reported by the Financial Times shows $856 billion of compute and infrastructure spending from 2026 through 2030. Both companies are growing at a pace with few precedents, and both are making commitments that assume it continues.
An efficiency shock. DeepSeek in 2025 and Kimi K3 this summer showed how fast the market will reprice the whole stack on the idea that AI might need less hardware. So far cheaper AI has led to more AI use rather than less spending, but that is an observation, not a law.
Capacity catching up. The quietest risk, and historically the most reliable one. Shortages end when supply arrives, and the equipment makers' record orders are, by definition, the cure for today's shortages. Memory in particular has a long history of going from shortage to glut within a couple of years.
The signals worth tracking are hyperscaler capex guidance each quarter, the labs' revenue against their commitments, credit spreads on the most indebted buyers, memory contract prices and lead times for power equipment.
A closer look: who gets paid when a chip is made
You don't need semiconductor physics to invest in this chain, but seeing the factory floor once explains why the bottom layers have so much leverage. An advanced chip passes through hundreds of process steps, most of them repeated loops: lay down a film, coat it with resist, print a pattern, etch it, polish it, inspect it, and repeat for the next layer. Each step is its own small market, and most are dominated by a few suppliers.
| Step | What happens | Who sells the tools or materials | Leading-edge suppliers |
|---|---|---|---|
| Design | Engineers lay out billions of transistors in software, often on licensed CPU cores | Cadence, Synopsys, Siemens; Arm for cores | 2 to 3 |
| Wafers | Ultra-pure silicon crystals are sliced and polished into 300mm wafers | Shin-Etsu, SUMCO, GlobalWafers, Siltronic, SK Siltron | 5, two lead |
| Deposition | Films of insulator or metal, sometimes one atomic layer thick, are laid down | Applied Materials, Lam Research, Tokyo Electron, ASM International | 3 to 4 |
| Resist and lithography | Resist is spun on, then a scanner prints the circuit pattern through a mask | ASML for EUV scanners; Tokyo Electron for about 90% of coating tools; Tokyo Ohka Kogyo, JSR and Shin-Etsu for resist | 1 for EUV |
| Etch | Plasma carves the printed pattern into the film below | Lam Research, Tokyo Electron, Applied Materials | 3 |
| Polish and clean | Chemical-mechanical planarization flattens each layer | Applied Materials, Ebara; Entegris and Qnity for slurries and pads | 2 to 3 |
| Inspection | Wafers are scanned for defects that would kill yield | KLA, with Applied, Onto and Nova in niches | 1 leads |
| Packaging | Dies are cut apart and joined to HBM on a shared base | TSMC (CoWoS), ASE, Amkor; Disco and Besi make key tools | 1 at scale for AI |
| Test | Chips are tested on the wafer and again after packaging | Advantest, Teradyne | 2 |
The single-supplier steps are real monopolies. If ASML stopped shipping EUV scanners, no one anywhere could make a leading-edge chip. And packaging, once the dullest step in the process, has become one of the tightest constraints in the whole build.
Five questions to ask before you buy a layer
One. How many companies can do this job at the leading edge? Pricing power lives where alternatives don't. One EUV supplier, two design-software vendors, three HBM makers: those counts say more about future margins than any single quarter.
Two. Is this layer the bottleneck now, or was it last year? The money in this cycle has followed the binding constraint. But constraints get solved, and the solution is always more capacity. A layer's best year is often the year its customers are panic-buying, which is also the year its suppliers order the tools that will end the shortage.
Three. How much of the revenue is AI, and do you want that? AI purity made power and optics stocks soar, and it made them fall hardest on DeepSeek day. Diversified suppliers like the big equipment makers lagged in the good years and held up in the scares.
Four. Who is paying, and with whose money? Check customer concentration in the filings, then check how those customers fund their purchases. Spending paid from operating cash flow behaves differently from spending paid with bonds, private credit and vendor financing.
Five. What is already in the price? The design-software duopoly has the best moat in the chain and has been one of its weaker investments since 2022. Memory has the weakest moat and the best returns. With cyclical businesses the trap also runs the other way: earnings peak when the shortage peaks, so the price-to-earnings ratio looks cheapest exactly when the cycle is most stretched.
How to get exposure
Many of the deepest-moat companies trade only in Tokyo, Seoul or Amsterdam, and some can't be bought at all. This is a map of who sits where, not a list of recommendations.
| Layer | U.S.-listed stocks and ADRs | Listed abroad, or private |
|---|---|---|
| Spenders | MSFT, GOOGL, AMZN, META, ORCL, CRWV, NBIS, SPCX | OpenAI, Anthropic (private) |
| Chip designers | NVDA, AMD, AVGO, MRVL, CBRS | SambaNova, Tenstorrent (private) |
| Design software and IP | CDNS, SNPS, ARM | Siemens EDA (inside Siemens) |
| Foundry | TSM, INTC, GFS | Samsung Electronics (005930.KS) |
| Memory | MU, SNDK | SK Hynix (000660.KS), Samsung |
| Packaging and test | ASX, AMKR, TER, ATEYY | Advantest (6857.T), Disco (6146.T), Besi (BESI.AS) |
| Equipment | ASML, AMAT, LRCX, KLAC, TOELY | Tokyo Electron (8035.T), ASM International (ASM.AS) |
| Materials | ENTG, Q, LIN, SHECY | Shin-Etsu (4063.T), SUMCO (3436.T), Tokyo Ohka Kogyo (4186.T); Zeiss, Trumpf, JSR (private) |
| Networking and optics | ANET, COHR, LITE, FN, CRDO, ALAB | |
| Power and cooling | VRT, ETN, GEV, CEG, VST | Schneider Electric (SU.PA), Siemens Energy (ENR.DE) |
| Data center REITs | EQIX, DLR |
If you would rather own a whole layer, semiconductors are well served and most other layers are not.
The VanEck Semiconductor ETF (SMH, 0.35 percent expense ratio) is the largest, with about $76 billion in 25 stocks, and the most concentrated: Nvidia is near 19 percent and TSMC about 9 percent. The iShares Semiconductor ETF (SOXX, 0.33 percent) caps its giants and currently leans toward Intel, AMD and Micron, further down the stack. The Invesco PHLX Semiconductor ETF (SOXQ, 0.19 percent) is the cheapest. Since ChatGPT launched, SMH has returned 443 percent and SOXX 346 percent. The equal-weighted SPDR S&P Semiconductor ETF (XSD) has returned 188 percent, because its tilt toward smaller companies missed a cycle in which the biggest gains went to the biggest names.
Outside silicon, the First Trust NASDAQ Clean Edge Smart Grid Infrastructure ETF (GRID) and the Defiance AI & Power Infrastructure ETF (AIPO) both hold Quanta Services and Eaton among their largest positions. The Global X Data Center & Digital Infrastructure ETF (DTCR) is mostly data center and tower REITs. VanEck's Data Center Supply Chain ETF (RACK), launched in June, bundles chips, power and cooling into one fund, but it is still small, with about $83 million in assets.
No clean U.S.-listed fund covers memory, equipment or materials on their own. For those layers you will be buying individual stocks or ADRs.
The bottom line
The AI supply chain isn't one trade, and the last four years prove it. The money entered at the top and has worked its way down, rewarding whichever layer was scarcest at the time: accelerators, then power and networking, then memory, optics and the machines that make chips. The deepest moats were not the best investments, and the most AI exposure was not the safest.
The habit worth keeping is to ask three things about any layer: where the bottleneck is now, who is paying to relieve it, and what happens to that layer's pricing once relief arrives. The answers will change again. They always have.
How we measured: returns are price returns from daily closes, split-adjusted and excluding dividends, through October 1, 2026. Each layer's figure is the median of the U.S.-listed stocks listed under it in the rotation chart. Company figures come from each company's most recent earnings release or filing; industry estimates are attributed in the text.
This piece is for informational purposes only and is not investment advice. Figures are as of October 2, 2026, and in this industry they move quickly.
Comments (0)
No comments yet. Be the first.